How Interest Rates Change the Total Cost of a Loan
Two loans with the same principal can have very different total costs. The rate matters, but so do the term, repayment method, payment frequency, insurance and one-time fees. A lower monthly payment may simply mean that the debt lasts longer. Flowjar helps you model the cash-flow effect; it does not replace the official disclosure or contract.
Separate the payment from the total cost
The periodic payment is what leaves your account on each due date. Total cost includes all payments plus interest and applicable fees over the full term. A longer term can reduce pressure this month while increasing the number of months in which interest accrues. A variable rate can make a later payment different from the first illustration.
Before comparing offers, write down the same principal, term and repayment assumptions for each one. Ask whether the quoted rate is fixed, variable, promotional or conditional. Check whether the advertised payment excludes insurance, administration, taxes or a final larger payment.
Record assumptions in Flowjar
Enter the official payment dates and amounts into your bills when the agreement is confirmed. For an estimate, create a clearly labelled scenario and record the rate, term, source and calculation date. Note uncertain fees and the date on which a rate may change. This keeps a forecast useful without making a hypothetical number look like a confirmed obligation.
Run the forecast over the full period, not only the first month. Test delayed income, a higher rate and a necessary one-off cost. Review both the lowest projected balance and the total amount paid. If the result depends on an optimistic income date or a buffer of zero, pause and investigate rather than treating the model as approval.
Questions worth asking the lender
Request the annual percentage rate or equivalent total-cost disclosure, the payment schedule, adjustment formula, setup and account fees, insurance requirements, late charges, early repayment terms and final-payment rules. Ask what happens if the payment date or interest rate changes. Keep the official documents with your records and update Flowjar only when a confirmed change occurs.
See Flowjar for planning and compare this with the Flowjar installment payment guide. Flowjar is not a bank, lender or financial adviser, and the contract remains the authoritative source.
Note: This article explains planning concepts only. It is not financial advice and does not predict approval or affordability.
A practical workflow for this topic
When you search for “How Interest Rates Change the Total Cost of a Loan”, the useful answer is usually a repeatable way to check the detail that matters. Use this Flowjar guide as a starting point, then confirm the current source before acting. The product can organize information and shorten a review; it cannot fill in missing facts or replace a professional decision.
Quick checklist before you act
- Choose the time window you are planning for.
- Record income, bills and set-aside money before judging a daily limit.
- Compare the forecast with the lowest point and upcoming obligations.
- Recheck the plan after a bill, payday or large purchase changes.
Keep the decision traceable: record the version, date and source you relied on when the detail may change.
Detailed step-by-step workflow
This extended section turns “How Interest Rates Change the Total Cost of a Loan” into a repeatable Flowjar workflow. The goal is not to create a longer checklist for its own sake. It is to make the important inputs visible, show what should be checked first, and leave a useful record of what was known at the time. That approach is especially helpful for cash-flow planning, bills, savings and a safe-to-spend decision. Read the steps in order the first time, then return to the relevant step when the situation changes.
Step 1: Define the question and the record you need.
Start with this action in Flowjar, then pause long enough to verify the result against the original source or observation. For “How Interest Rates Change the Total Cost of a Loan”, record the date, the relevant context and anything that was not available. A structured record is more useful when another person can understand what was checked without guessing what happened between two screenshots, notes or exports.
Step 2: Gather the original inputs before interpreting the result.
Start with this action in Flowjar, then pause long enough to verify the result against the original source or observation. For “How Interest Rates Change the Total Cost of a Loan”, record the date, the relevant context and anything that was not available. A structured record is more useful when another person can understand what was checked without guessing what happened between two screenshots, notes or exports.
Step 3: Review the result and record uncertainty or missing data.
Start with this action in Flowjar, then pause long enough to verify the result against the original source or observation. For “How Interest Rates Change the Total Cost of a Loan”, record the date, the relevant context and anything that was not available. A structured record is more useful when another person can understand what was checked without guessing what happened between two screenshots, notes or exports.
Step 4: Save the version, date and next action for later comparison.
Start with this action in Flowjar, then pause long enough to verify the result against the original source or observation. For “How Interest Rates Change the Total Cost of a Loan”, record the date, the relevant context and anything that was not available. A structured record is more useful when another person can understand what was checked without guessing what happened between two screenshots, notes or exports.
Quality checks and common mistakes
Long-form guidance is most useful when it explains the boundaries as well as the happy path. Before relying on a Flowjar record, run the checks below. They help separate a missing input from a negative result, an approximate value from a verified value, and a convenient summary from the original evidence.
Check 1
Do not start with the conclusion. Write down the question, the person or property involved and the time period first. In Flowjar, keep the source, context and limitation close to the record so the next review can reproduce the decision.
Check 2
Do not mix old and new records without a date. Keep the original observation visible when you add a correction or update. In Flowjar, keep the source, context and limitation close to the record so the next review can reproduce the decision.
Check 3
Do not treat a missing field as proof that the event, ingredient, expense or condition does not exist. In Flowjar, keep the source, context and limitation close to the record so the next review can reproduce the decision.
Check 4
Do not share a polished summary before checking the original image, note, label, receipt or export behind it. In Flowjar, keep the source, context and limitation close to the record so the next review can reproduce the decision.
Check 5
Do not use an app record as a substitute for a professional, medical, legal, financial or safety decision when the situation requires one. In Flowjar, keep the source, context and limitation close to the record so the next review can reproduce the decision.
Frequently asked questions
What should I verify before I rely on this guide?
For “How Interest Rates Change the Total Cost of a Loan”, use Flowjar to organize the observation and then verify the part that affects the decision. If a source, image, measurement or input is incomplete, mark it as incomplete instead of silently filling the gap. Add a date and a short note about the method used. When the consequence is important or the question sits outside the product’s purpose, confirm it with the current official source or an appropriate professional.
What should I do when the information is incomplete?
For “How Interest Rates Change the Total Cost of a Loan”, use Flowjar to organize the observation and then verify the part that affects the decision. If a source, image, measurement or input is incomplete, mark it as incomplete instead of silently filling the gap. Add a date and a short note about the method used. When the consequence is important or the question sits outside the product’s purpose, confirm it with the current official source or an appropriate professional.
How can I make the record easier to compare later?
For “How Interest Rates Change the Total Cost of a Loan”, use Flowjar to organize the observation and then verify the part that affects the decision. If a source, image, measurement or input is incomplete, mark it as incomplete instead of silently filling the gap. Add a date and a short note about the method used. When the consequence is important or the question sits outside the product’s purpose, confirm it with the current official source or an appropriate professional.
When should I ask for another source or a specialist?
For “How Interest Rates Change the Total Cost of a Loan”, use Flowjar to organize the observation and then verify the part that affects the decision. If a source, image, measurement or input is incomplete, mark it as incomplete instead of silently filling the gap. Add a date and a short note about the method used. When the consequence is important or the question sits outside the product’s purpose, confirm it with the current official source or an appropriate professional.
A practical review before you finish
Before closing this topic, read the title “How Interest Rates Change the Total Cost of a Loan” as a question rather than a promise. Confirm the current version of the information, check the original evidence, and record the next action in Flowjar. A useful record says what was observed, when it was observed, what remains uncertain and who should review it next. This makes the article easier to apply today and easier to revisit when the facts change.
See the product in action
Related guides
How to Budget When Your Income Is Irregular
Manage freelance, seasonal or commission income with a minimum plan, buffers, bills and forecast scenarios in Flowjar.
What are money jars? How to divide each payday
Learn how money jars work for bills, spending and goals, and how Flowjar helps you track progress without making a plan too complex.
How to Use the Flowjar Loan Calculator Correctly
Use a loan calculator with the Flowjar forecast without confusing an estimated payment with the full cost or real obligation.
Feature walkthroughs
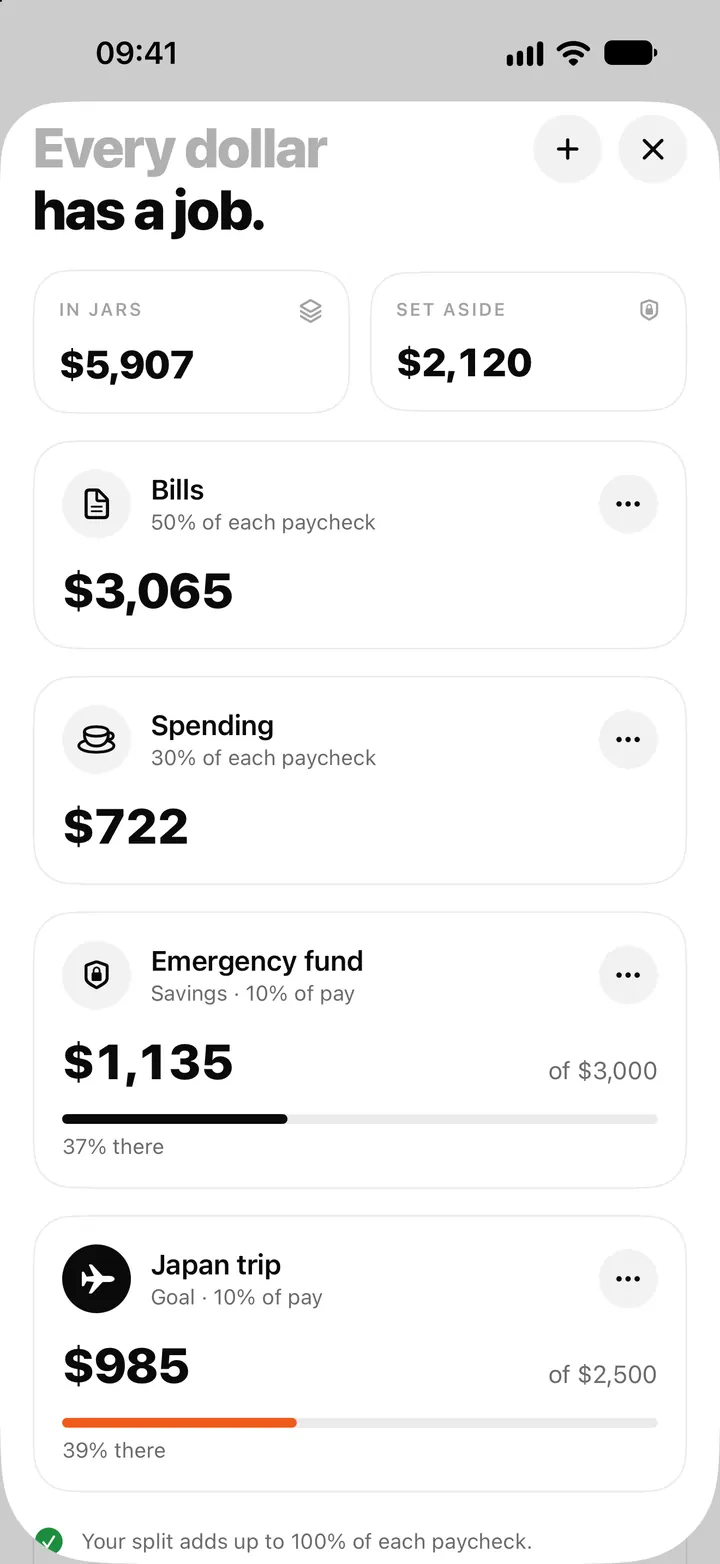
Money jars in Flowjar: split each paycheck into bills, spending and savings
Flowjar splits each paycheck across jars for bills, spending, savings and goals. Learn the four jar types, how shares work and what each does to Safe to spend.
Read
Fill my jars: log your paycheck and split it on payday in Flowjar
Flowjar never logs your paycheck by itself. On payday, add it as income with Fill my jars on and it is shared across your jars. Here is how, plus side income.
Read
Move money between jars in Flowjar: Add to jar, Take out and Paid from jar
Move money in or out of a Flowjar jar, pick which jar an expense is paid from, and see what each move does to your balance, Set aside and Safe to spend.
Read